

In this post we discuss an emerging Malaysian photonics manufacturing partner that stands to benefit from the need to diversify away from optical transceiver manufacturing in China.
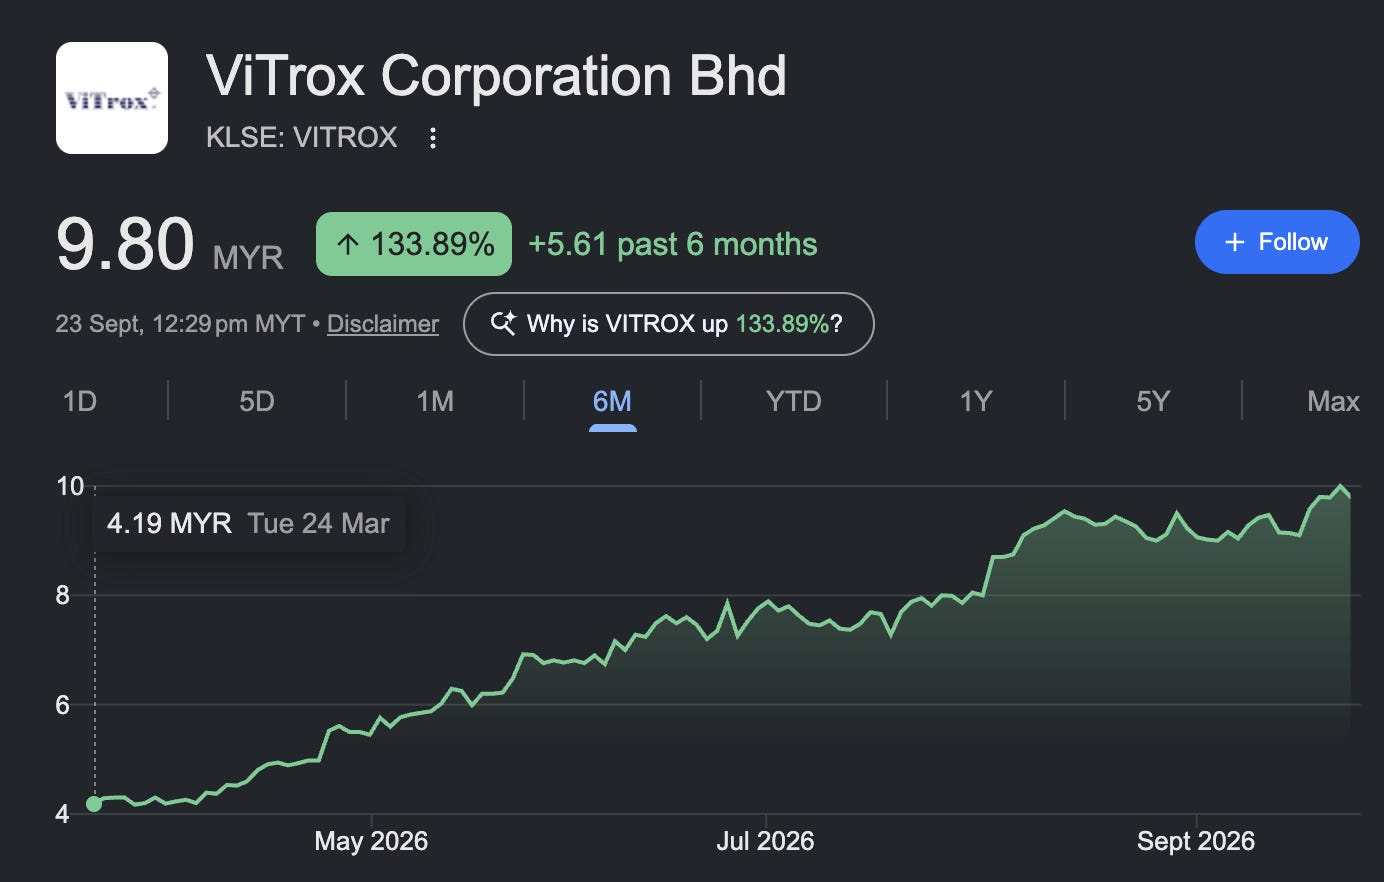
As we’ve pointed out a few times before, Malaysian semiconductor stocks have been remarkably resilient, and many did not pull back in July at all. It appears that capital is longer duration and semis / DCs/ manufacturing probably has little competition with other sectors as a destination for investment.
ViTrox is a notable example:
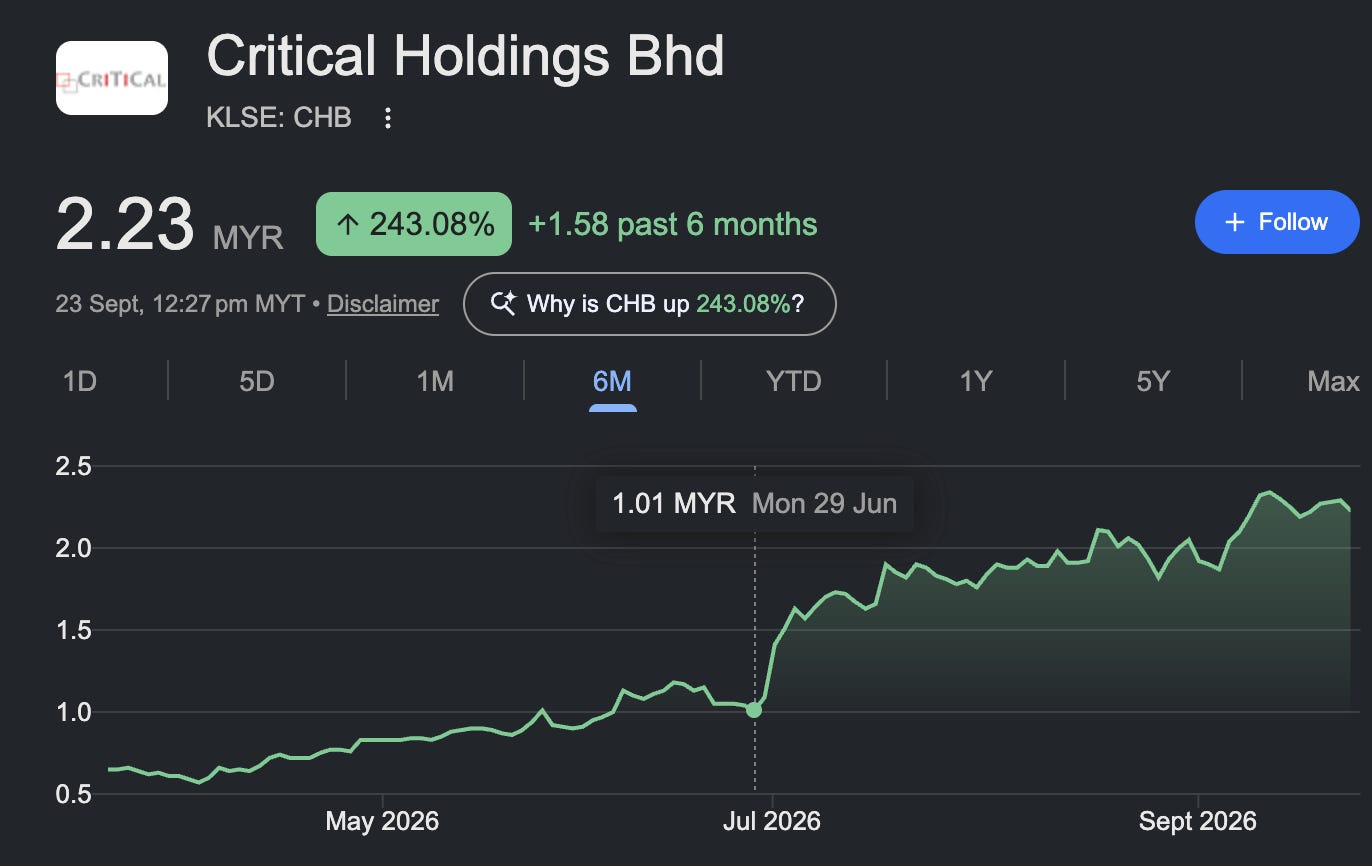
Earlier this year, we also flagged a small cleanroom contractor that has doubled since July, which speaks to the amount of investment happening in Malaysia.
By popular request, we’re presenting a bull/bear case for a company that is working with US photonics players like Lumentum and Coherent. If you’ve been following photonics, you’ll understand that demand is not in question - this company will get as many orders as it can reliably deliver, and so its ability to multibag arguably turns only on execution.
I think I should also caveat this by saying that I have not personally met the company or checked the numbers shared with me below, but I did think it was worth publishing because of the identity of the people who shared the idea - there is pretty serious attention on this stock.